
Key Takeaways
- IDB Lab’s $5M debt facility to Paigo—part of a potential $10M package—targets Uruguay’s MSME credit gap, where over 90% of firms are small businesses historically shut out of formal lending.
- Paigo’s alternative-data model uses payment platform integration to tie loan repayments to real cash flow, replacing collateral requirements and potentially reducing the fourfold capital penalty banks face on unrated small-business exposure.
- This development capital signals institutional maturity in Uruguay’s digital payments infrastructure, a leading indicator for broader credit expansion, commercial rent stability, and property demand.
Table of Contents
A $5 Million Fintech Loan That Redraws Uruguay’s Credit Map
Montevideo-based Paigo has secured a debt facility of up to $5 million from IDB Lab, the innovation and venture arm of the Inter-American Development Bank Group. Dealroom.co was first to identify the structure, which will expand productive credit for micro, small, and medium-sized enterprises across Uruguay. It is the initial slice of a wider package that could reach $10 million.
This is not a conventional venture capital round. The money is development capital aimed at scaling loans to businesses that have been shut out of formal lending. That distinction matters for anyone assessing the depth and stability of Uruguay’s domestic economy.
More than 90% of Uruguayan companies are MSMEs, yet most have lacked a practical path to credit. Paigo’s model targets that gap directly, with a specific focus on women-led businesses, founders without credit history, and firms whose cash flows do not fit traditional collateral requirements.
How Alternative Data Becomes Working Capital for Small Firms
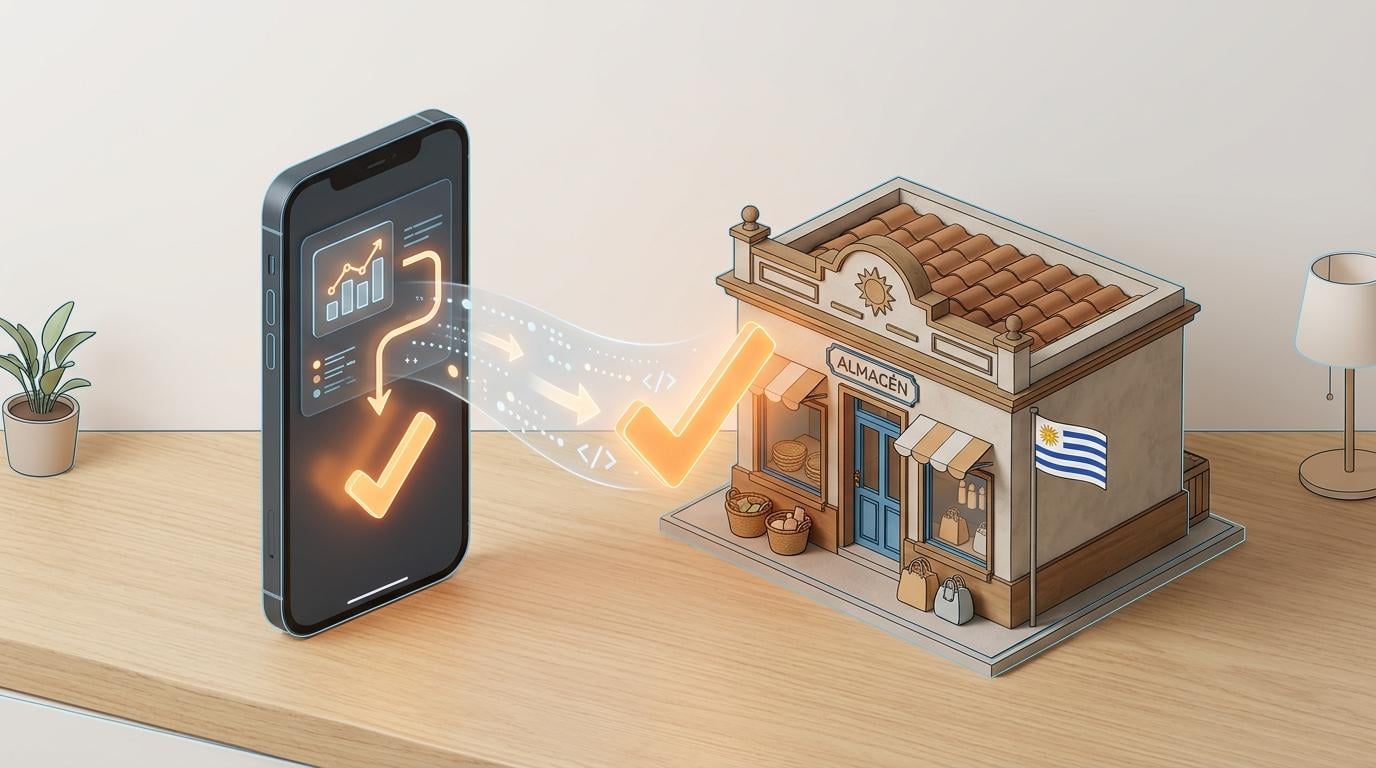
Paigo, founded in 2018, uses alternative data, analytics, and AI models to assess credit risk for small businesses. Its MSME product integrates with payment platforms such as Handy, pulling sales and transaction data to size loans and tie repayments to each company’s real cash flow—a structure first identified by Dealroom.co.
This approach replaces the traditional underwriting demand for hard collateral and long banking histories. A small retailer that processes daily payments through a digital platform can now be scored on the rhythm of those receipts rather than on the value of real estate it does not own.
IDB Lab’s backing forms part of a package signed at the GET Forum in Quito, where the Inter-American Development Bank Group committed up to $24 million across three operations. The official IDB release describes the Paigo operation as a $10 million loan, while the initial $5 million facility outlined in the market data has not been separately itemized in that release.
That discrepancy does not change the core signal: the structure likely involves an initial tranche and a contingent follow-on. For investors, the more important point is that multilateral development capital is now underwriting a data-driven lending model in Uruguay, a small market that is often overlooked in regional fintech conversations.
The regional gap is wide. The IDB estimates nearly half of formal small and medium-sized businesses in Latin America and the Caribbean face financial constraints. World Bank Group President Ajay Banga put the global financing gap for developing-country MSMEs above $4 trillion per year in a speech at the October 2026 Annual Meetings in Bangkok.
Fintech alternative-data lending has already reached roughly $400 billion in emerging markets, with AI-driven approvals often delivered within 24 hours. Cash flow, not collateral, is becoming the single most reliable indicator of repayment ability. For Uruguay, a country where more than 90% of firms are small businesses, that shift has real economic weight.
Our Read: Development Capital as a Signal for Uruguay’s Business Density
We read this transaction less as a fintech story and more as a signal about Uruguay’s underlying business density. When a multilateral lender such as IDB Lab puts development capital behind a cash-flow-based credit model, it is making a quiet bet that Uruguay’s small-business payments data is rich enough to support disciplined underwriting.
That has consequences beyond the fintech sector. A broader base of MSMEs with access to working capital tends to stabilize commercial rents, support neighborhood retail, and create more predictable demand for small industrial and logistics spaces. In our experience advising international investors, these are the micro-dynamics that get lost in headline GDP figures.
Two figures are worth flagging: the market data points to an initial $5 million facility with a second $5 million possible later, while the official IDB announcement describes a $10 million loan. We treat the lower figure as the near-term commitment and the upper figure as the full structure if Paigo meets performance conditions. Investors should not overstate the immediate scale, but they also should not miss the direction of travel.
Paigo’s stated focus on women-led businesses and founders without credit history adds a social layer that multilateral lenders prize. That does not make the loan concessionary by definition; it makes it development capital with measurable financial inclusion targets. For a small, stable market like Uruguay, this kind of instrument can attract follow-on private credit and deepen the formal economy.
World Bank data reinforces the mechanism: a bank holding unrated small-business exposure must set aside roughly four times more capital than for a local AAA-rated corporate loan. Alternative data can narrow that gap, and any meaningful reduction in lending friction tends to lift the value of productive assets over time.
From Microcredit to Property Markets: The Long View
Uruguay has long marketed itself as a safe harbor for capital, but safety without liquidity is incomplete. A functioning MSME credit channel adds the missing layer: it turns daily sales data into working capital, which in turn supports the small enterprises that occupy commercial real estate and drive domestic demand.
For international investors, the Paigo facility is a marker of institutional maturity. It signals that multilateral lenders view Uruguay’s digital payments infrastructure not as a promise but as a substrate for real underwriting. That is exactly the kind of signal that precedes broader credit expansion and, eventually, more stable property yields.
There is one risk on the buying side worth flagging: dual agency. In some property transactions, a single agent may represent both the buyer and the seller, which creates a structural conflict of interest, leading to inflated valuations, hidden liabilities, or softened negotiation because the agent’s incentive is to close the deal rather than protect one client. For anyone moving capital into Uruguay, insisting on separate representation is a non-negotiable first step.
At Team Haverkate, we track financial-sector shifts like this because a deeper credit market changes who can buy, hold, and improve real assets. For international buyers and investors assessing Uruguay, that means reading fintech news not as a separate sector story but as a leading indicator for property demand and commercial stability. We also maintain close relationships with vetted local tax and legal specialists for anyone structuring a cross-border entry into Uruguay’s financial or real estate ecosystem.
Frequently Asked Questions
What is the Paigo loan from IDB Lab and how large is it?
Paigo, a Montevideo-based fintech founded in 2018, secured a debt facility of up to $5 million from IDB Lab, the innovation arm of the Inter-American Development Bank Group. It is the initial tranche of a wider package that could reach $10 million, which the official IDB release describes as a $10 million loan. The capital is development capital aimed at expanding productive credit for micro, small, and medium-sized enterprises across Uruguay, not a conventional venture capital round.
How does Paigo lend to small businesses without collateral or credit history?
Paigo uses alternative data, analytics, and AI models to assess credit risk. Its MSME product integrates with payment platforms such as Handy, pulling sales and transaction data to size loans and tie repayments to each company’s real cash flow. This replaces the traditional underwriting demand for hard collateral and long banking histories, allowing a small retailer to be scored on the rhythm of its digital receipts rather than on real estate it does not own.
Why does MSME credit access matter for Uruguay’s economy?
More than 90% of Uruguayan companies are MSMEs, yet most have lacked a practical path to credit. The IDB estimates nearly half of formal small and medium-sized businesses in Latin America and the Caribbean face financial constraints, and the World Bank puts the global financing gap for developing-country MSMEs above $4 trillion per year. Broader access to working capital tends to stabilize commercial rents, support neighborhood retail, and create more predictable demand for small industrial and logistics spaces.
Who does Paigo specifically target with its lending model?
Paigo focuses on businesses shut out of formal lending, with a specific emphasis on women-led businesses, founders without credit history, and firms whose cash flows do not fit traditional collateral requirements. This social layer is prized by multilateral lenders and makes the facility development capital with measurable financial inclusion targets rather than a purely commercial loan.
Why is development capital from IDB Lab a signal for Uruguay’s property market?
When a multilateral lender backs a cash-flow-based credit model, it signals that Uruguay’s small-business payments data is rich enough to support disciplined underwriting. A functioning MSME credit channel turns daily sales data into working capital, supporting the small enterprises that occupy commercial real estate and drive domestic demand. For international investors, this institutional maturity is a leading indicator for property demand and commercial stability.
What is the difference between the $5 million facility and the $10 million IDB loan?
Market data points to an initial $5 million facility with a second $5 million possible later, while the official IDB announcement describes a $10 million loan. The structure likely involves an initial tranche and a contingent follow-on. Investors should treat the lower figure as the near-term commitment and the upper figure as the full structure if Paigo meets performance conditions, without overstating the immediate scale.
What risk should international buyers watch for in Uruguayan property transactions?
Dual agency is a key risk: in some transactions a single agent represents both buyer and seller, creating a structural conflict of interest. International buyers can face inflated valuations, hidden liabilities, or softened negotiation because the agent’s incentive is to close the deal rather than protect one client. Insisting on separate representation is a non-negotiable first step for anyone moving capital into Uruguay.