
Key Takeaways
- Uruguay recorded 13 private capital transactions through July 2026, following a record 33 deals in 2025, with technology and services alone accounting for six of this year’s operations.
- Institutional capital is targeting hard assets: JHSF acquired Enjoy Punta del Este and Kopel Sánchez partnered with Estudio Luis E. Lecueder on the El Águila joint venture in Atlántida, signaling confidence in Uruguay’s coastal real estate.
- The IMF projects only 1.3 percent GDP growth in 2026 and 1.2 percent average annual growth since 2016, so active deal flow is running alongside an economy that still needs structural acceleration to fully monetize assets.
Table of Contents
A 13-Deal Signal for Uruguay Private Capital Momentum
Thirteen private capital transactions were identified across Uruguay in the opening months of 2026, spanning pharmaceuticals, tourism, energy, technology and startup capitalization. The figure comes from Uruguay XXI and covers activity through July, so it represents a partial-year snapshot rather than a complete annual count.
That level of deal flow extends the market’s momentum after a record 33 transactions in 2025 and suggests that international investors continue to allocate capital to Uruguay across both established assets and early-stage platforms.
The more relevant signal for international investors is sectoral breadth. Capital is moving into regulated healthcare, hard tourism infrastructure, renewable and offshore energy, and venture-stage innovation at the same time.
Where the 2026 Deals Are Concentrating
The Uruguay XXI report classifies the 13 operations across acquisitions, minority investments, capitalization rounds and joint ventures. That structural mix matters because each channel carries a different risk, control and return profile for cross-border capital.
Several of the most visible deals involved mature assets changing hands. In pharmaceuticals, Humanova Lab Corporation acquired Farmaco Uruguayo, while Farmacity purchased FarmaGlobal. The tourism sector recorded JHSF’s acquisition of Enjoy Punta del Este, a coastal hospitality asset. In renewable energy, Ardian acquired solar assets.
Offshore exploration also attracted institutional positioning, with QatarEnergy and Chevron participating in oil exploration blocks. Those energy moves sit alongside Uruguay’s established renewable generation base rather than replacing it.
- Startup capital: Horizon received investment from NXTP Labs, EWA Capital and private investors; Viatik added Plug and Play Ventures.
- Health and biotech: Antarka drew Brazilian and South Korean investors, while MetaBIX Biotech completed a third capitalization round with Latin American funds and the Uruguayan government.
- Urban development: Kopel Sánchez and Estudio Luis E. Lecueder formed a joint venture for the El Águila project in Atlántida.
Technology and services accounted for six of the 13 operations identified so far in 2026. That concentration follows a broader pattern: in 2025, those activities represented 19 of 33 transactions.
The dataset is not exhaustive. Uruguay lacks a central registry for private capital and mergers and acquisitions, so the report is assembled from specialized databases, regulatory filings, institutional contacts and journalistic sources. The 2026 figures are preliminary and should not be directly compared with full-year results.
Team Haverkate’s Read: Capital Flows Meet Macro Discipline
Team Haverkate has observed that private capital activity is holding up within a deliberately conservative macro adjustment. According to the IMF‘s September 2026 Article IV statement, GDP growth is projected at 1.3 percent in 2026 after 1.8 percent in 2025, with a drought-driven agricultural contraction masking an economy otherwise operating near potential. The fund expects growth to recover to 2.4 percent in 2027 as the output gap narrows.
Inflation held at 4.6 percent in August 2026, effectively at the central bank’s 4.5 percent target, while international reserves covered 11.25 months of imports. Sovereign spreads remain the lowest in the region and near historical lows, backed by investment-grade credit ratings.
Domestic credit reinforces the picture. Real peso credit expanded around 9 percent year-over-year in August 2026, with non-performing loans low and bank capital ratios roughly double regulatory minimums. This is not an economy starved of local financing; it is one where asset purchases can be paired with domestic liquidity.
Yet the same IMF assessment carries a tension that should temper any narrative of easy upside. Uruguay’s growth has averaged only 1.2 percent per year since 2016, a pace the fund considers insufficient to converge toward advanced-economy income levels. The private capital pipeline is active, but the underlying economy still needs structural acceleration to fully monetize those assets.
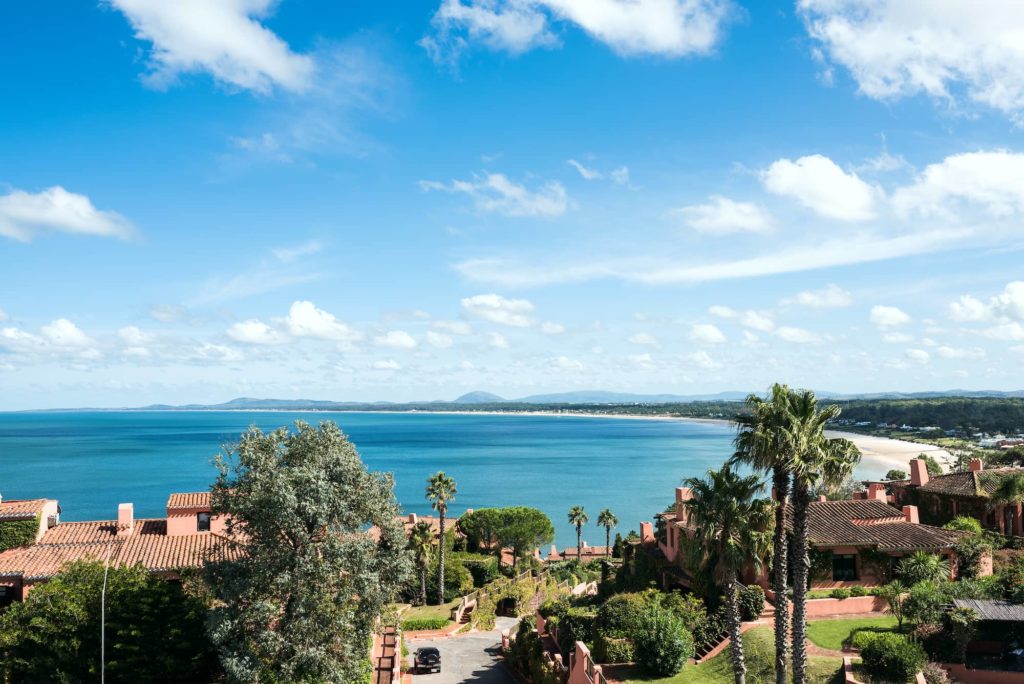
From a property investor’s viewpoint, the tourism and urban development deals are more than corporate news. JHSF’s move on Enjoy Punta del Este and the El Águila joint venture in Atlántida show institutional confidence in Uruguay’s coastal asset class, where transaction volumes are opaque but pricing power is increasingly visible.
Team Haverkate maintains excellent relationships with local tax, legal and transactional specialists experienced in cross-border property and corporate acquisitions. Investors considering private market entry are encouraged to reach out directly for an introduction.
Uruguay’s Next Phase as a Regional Capital Hub
Uruguay’s private capital market is moving from episodic deal flow to a more repeatable investment cycle. The mix of pharmaceutical consolidation, institutional solar ownership, offshore energy positioning and biotech capitalization suggests that international capital is treating Uruguay as a jurisdiction where regulatory stability can coexist with sector-specific value creation.
The 2026 data remains partial, and the 13 transactions identified through July should not be treated as a full-year projection. But the continuation after 2025’s record confirms that the pipeline is not dependent on a single sector or buyer profile.
International investors should nevertheless be cautious about dual agency in Uruguay’s real estate market. Dual agency occurs when the same broker or agency represents both buyer and seller in a transaction, creating a structural conflict of interest. That arrangement can compromise negotiation outcomes, mask value distortions or obscure liabilities that disciplined independent representation would surface.
For buyers seeking exposure to Uruguay’s private capital momentum through real estate, corporate acquisitions or development joint ventures, Team Haverkate offers on-the-ground guidance across due diligence, valuation and transaction structuring. The firm helps international investors navigate the market with independent, data-grounded judgment rather than promotional shortcuts.
Frequently Asked Questions
How many private capital deals were recorded in Uruguay in 2026?
Thirteen private capital transactions were identified across Uruguay in the opening months of 2026, according to Uruguay XXI, covering activity through July. That follows a record 33 transactions in 2025 and indicates continued international allocation to both established assets and early-stage platforms.
Which sectors attracted the most private capital in Uruguay in 2026?
Capital concentrated in pharmaceuticals, tourism, energy, technology and startup capitalization. Technology and services accounted for six of the 13 operations in 2026, following a pattern in 2025 when those activities represented 19 of 33 transactions. Healthcare, renewable and offshore energy, and venture-stage innovation also drew institutional investors simultaneously.
Is the 2026 Uruguay private capital deal data complete?
No. Uruguay lacks a central registry for private capital and mergers and acquisitions, so the Uruguay XXI report is assembled from specialized databases, regulatory filings, institutional contacts and journalistic sources. The 13 transactions identified through July are a partial-year snapshot and should not be compared directly with full-year results or treated as a full-year projection.
What do the IMF 2026 projections mean for investors in Uruguay?
The IMF September 2026 Article IV statement projects GDP growth of 1.3 percent in 2026 after 1.8 percent in 2025, with a drought-driven agricultural contraction masking an economy otherwise near potential, and recovery to 2.4 percent in 2027. Inflation held at 4.6 percent in August 2026 against a 4.5 percent target, reserves covered 11.25 months of imports, and sovereign spreads remain the lowest in the region. However, growth has averaged only 1.2 percent per year since 2016, which the fund considers insufficient for convergence to advanced-economy income levels.
Why does the JHSF acquisition of Enjoy Punta del Este matter for real estate investors?
The acquisition is a mature coastal hospitality asset changing hands, and together with the Kopel Sanchez and Estudio Luis E. Lecueder joint venture for the El Aguila project in Atlantida, it signals institutional confidence in Uruguay coastal real estate. Transaction volumes in that asset class are opaque, but pricing power is increasingly visible, making these deals a read on institutional demand rather than isolated corporate news.
What is dual agency and why does it matter when buying property in Uruguay?
Dual agency occurs when the same broker or agency represents both the buyer and the seller in a transaction, creating a structural conflict of interest. It can compromise negotiation outcomes, mask value distortions, or obscure liabilities that disciplined independent representation would surface, so buyers should confirm which side a broker represents before engaging.
How can international investors gain exposure to Uruguay private capital momentum?
Exposure can be pursued through real estate, corporate acquisitions, or development joint ventures. Real peso credit expanded around 9 percent year-over-year in August 2026 with low non-performing loans and bank capital ratios roughly double regulatory minimums, so asset purchases can be paired with domestic liquidity. On-the-ground guidance across due diligence, valuation and transaction structuring, plus local tax and legal specialists, helps investors avoid promotional shortcuts.