
Key Takeaways
- Eligible workers pay a flat 12% income tax instead of the progressive rate up to 36%, and can opt out of social security for up to five years.
- The regime requires at least two-thirds physical presence in Uruguay each year and salary-only income from a qualifying employer in tech, life sciences, or global services.
- The benefit is available only once, lasts five years, and disappears entirely if any condition fails, triggering unpaid taxes, penalties, and surcharges.
Table of Contents
A Flat 12% Rate With Real Conditions
A flat 12% income tax rate now sits at the center of Uruguay’s new qualified talent program, a five-year framework for workers who relocate for dependent roles in technology, innovation, and global services.
Eligible workers can choose that rate instead of the progressive personal income tax that reaches 36%, and they can opt out of social security contributions for up to five years. The measure was first reported by El Observador.
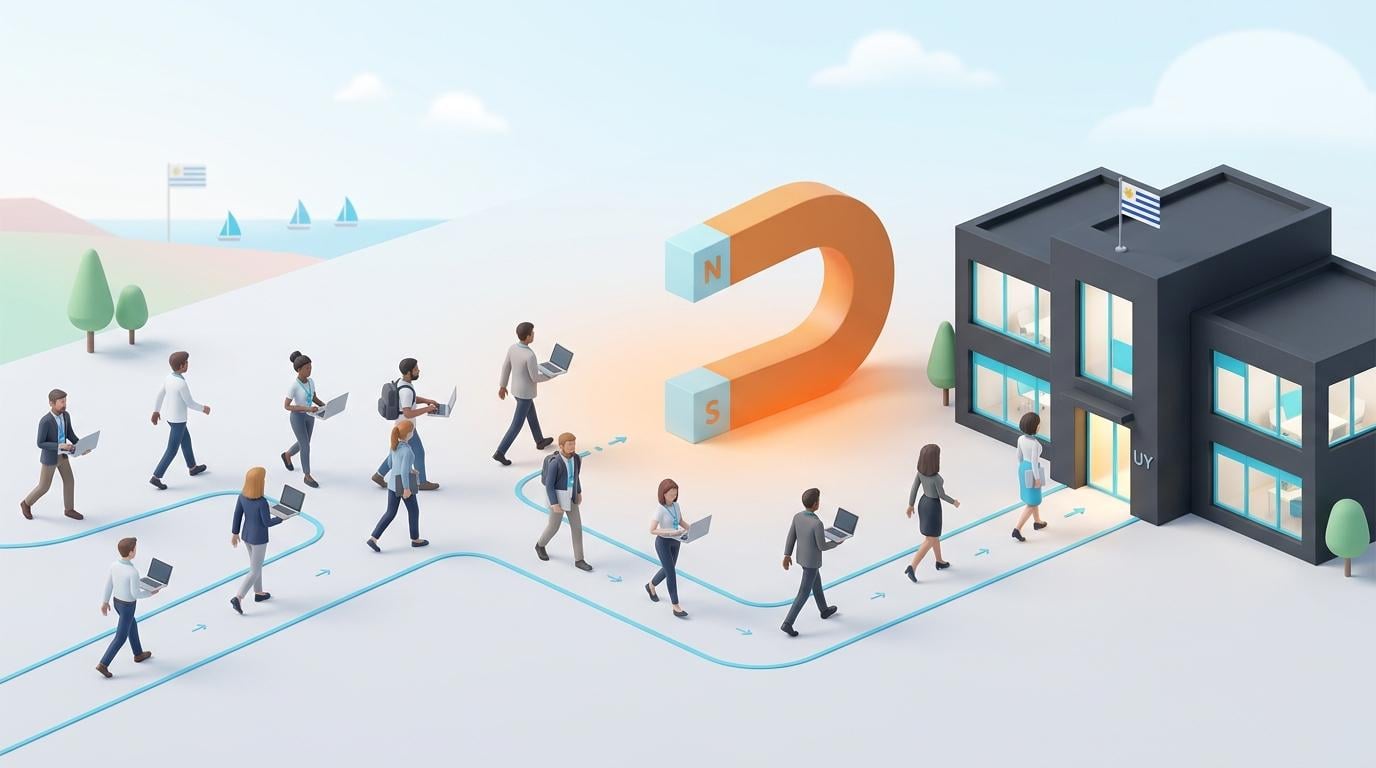
The program is aimed at people who physically relocate to Uruguay for dependent employment, not at remote contractors or passive investors. That distinction shapes the entire opportunity.
How the Regime Works on the Ground
Candidates must clear three main filters before choosing the flat rate.
- No previous tax residency: They cannot have been Uruguayan tax residents during the five fiscal years before relocating.
- Physical presence: They must stay in Uruguay for at least two-thirds of each calendar year, or of the contract period if the job does not span the full year.
- Salary-only income: All labor income must be earned in Uruguay and solely from dependent work.
The employer must also sit inside a defined set of activities. According to El Observador, the decree covers pharmaceutical, electronic, and medical instrument manufacturing; telecoms; computer programming; data processing; engineering; and certain research, financial, and educational operations.
Being registered is not enough. The company has to actually carry out the qualifying activity and hold active registrations with Uruguay’s tax office and social security bank.
The mechanics are deliberately front-loaded. A worker chooses the regime at the start of the employment relationship through a sworn statement, and the employer communicates that choice to the social security bank. Monthly withholding of the flat rate then falls to the employer, who must remit it to the tax office the following month.
Employers also take on monitoring duties. They must confirm the worker’s migration record each year and keep evidence that all conditions remain intact.
The benefit is available only once and lasts for the election year plus four more. Someone who began qualifying employment between 1 March and 31 December 2025 can join the regime if the Budget Law’s entry into force allows it.
Changing jobs is possible without losing the option. The worker has up to one year to start a new dependent position in a qualifying company, provided all other requirements still hold.
Noncompliance is abrupt. If any condition fails, the regime disappears for that fiscal year and subsequent ones, and unpaid taxes, penalties, and surcharges become due.
Team Haverkate’s Take: A Residency Planning Filter
From our vantage point advising international buyers and relocation candidates, this decree functions best as a screening tool for employment-led residency. It is not a broad tax holiday for investors, retirees, or independent professionals.
The two-thirds physical presence rule is the spine of the program. That is a genuine stay test, not a paper residency formality. Anyone hoping to hold the benefit while living elsewhere will trip the trigger quickly.
We also read the employer side carefully. Because companies must verify migration movements and withhold the flat rate, the administrative burden will likely favor established employers in technology, life sciences, and global services that already run structured payrolls and compliance teams.
For a high-income employee relocating from the US, Germany, Switzerland, or Austria, the difference between the flat rate and the top personal income rate can be significant. But the benefit is tied to salary only. Rental income, investment gains, and self-employment are outside this structure.
The five-year ceiling is best understood as a settlement runway. It gives a qualified professional enough time to establish a household, build a Uruguayan property position, and decide whether to remain under ordinary tax rules after the window closes.
A Five-Year Window, Not a Permanent Door
Uruguay has chosen a disciplined, narrow instrument. It rewards people who move for qualifying employment, live in the country, and earn salary income, without creating a permanent low-tax class.
That restraint matters for Uruguay’s reputation with foreign investors and institutions. The program does not undermine the ordinary tax base; it trades a temporary reduction for real physical presence and employer accountability.
After the five-year runway, the standard personal income tax and social security rules return. Planning should therefore target the window as a relocation incentive, not as a substitute for a permanent tax residency strategy.
There is one risk on the buying side worth flagging for anyone who turns this tax window into a Uruguay property purchase: dual agency. In some local transactions, one agent represents both buyer and seller, a structure that can soften negotiation on price, conceal property liabilities, and leave the investor without a clear fiduciary advocate. Always insist on separate representation.
As the regime takes effect, Team Haverkate can help international buyers and professionals understand how a five-year tax plan fits with the realities of Uruguay’s residential market. For clients structuring a cross-border entry under this new program, we work alongside vetted local tax and legal specialists to align property decisions with residency and employment requirements.
Frequently Asked Questions
What is Uruguay’s new 12% flat tax regime for qualified talent?
It is a five-year program that lets eligible foreign workers who relocate to Uruguay for dependent employment in technology, innovation, and global services pay a flat 12% income tax instead of the progressive rate that reaches 36%. Participants can also opt out of social security contributions for up to five years.
Who qualifies for Uruguay’s 12% income tax rate?
Candidates must not have been Uruguayan tax residents in the five fiscal years before relocating, must stay in Uruguay at least two-thirds of each calendar year, and must earn all labor income in Uruguay solely from dependent work. The employer must also operate in a qualifying activity such as telecoms, computer programming, data processing, engineering, or pharmaceutical and medical instrument manufacturing.
Does the 12% rate apply to remote contractors, investors, or retirees?
No. The regime is limited to people who physically relocate to Uruguay for dependent employment with a qualifying company. Remote contractors, passive investors, retirees, and self-employed professionals are excluded, and income such as rental income or investment gains falls outside the structure.
How long does Uruguay’s qualified talent tax benefit last?
The benefit lasts for the election year plus four more years, for a total of five years, and it can only be used once. After the window closes, standard personal income tax and social security rules apply again.
Can I change jobs and keep the 12% flat tax benefit?
Yes, provided the worker starts a new dependent position at a qualifying company within one year and all other requirements, including physical presence and salary-only income, remain satisfied.
What happens if a worker fails to meet the program conditions?
Noncompliance is abrupt. If any condition fails, the regime is lost for that fiscal year and subsequent years, and unpaid taxes, penalties, and surcharges become due. Employers must also verify the worker’s migration record annually and retain evidence that all conditions remain intact.
How does the two-thirds physical presence rule work?
Participants must stay in Uruguay for at least two-thirds of each calendar year, or of the contract period if the job does not span the full year. This is a genuine stay test rather than a paper residency formality, so anyone hoping to hold the benefit while living elsewhere will fail to qualify.