
Key Takeaways
- Uruguay’s $350M World Bank loan cuts interest by up to 100 basis points if livestock methane intensity targets are met, saving up to $12.5M.
- The performance-linked structure, a first for the World Bank, reinforces Uruguay’s investment-grade credibility with gross debt at 62.5% of GDP and the lowest sovereign spread in Latin America.
- For property investors, the loan signals stronger institutional quality and climate management, but dual agency risks in real estate transactions require careful due diligence.
Table of Contents
A $350 Million Borrowing Cost Tied to Methane Reductions
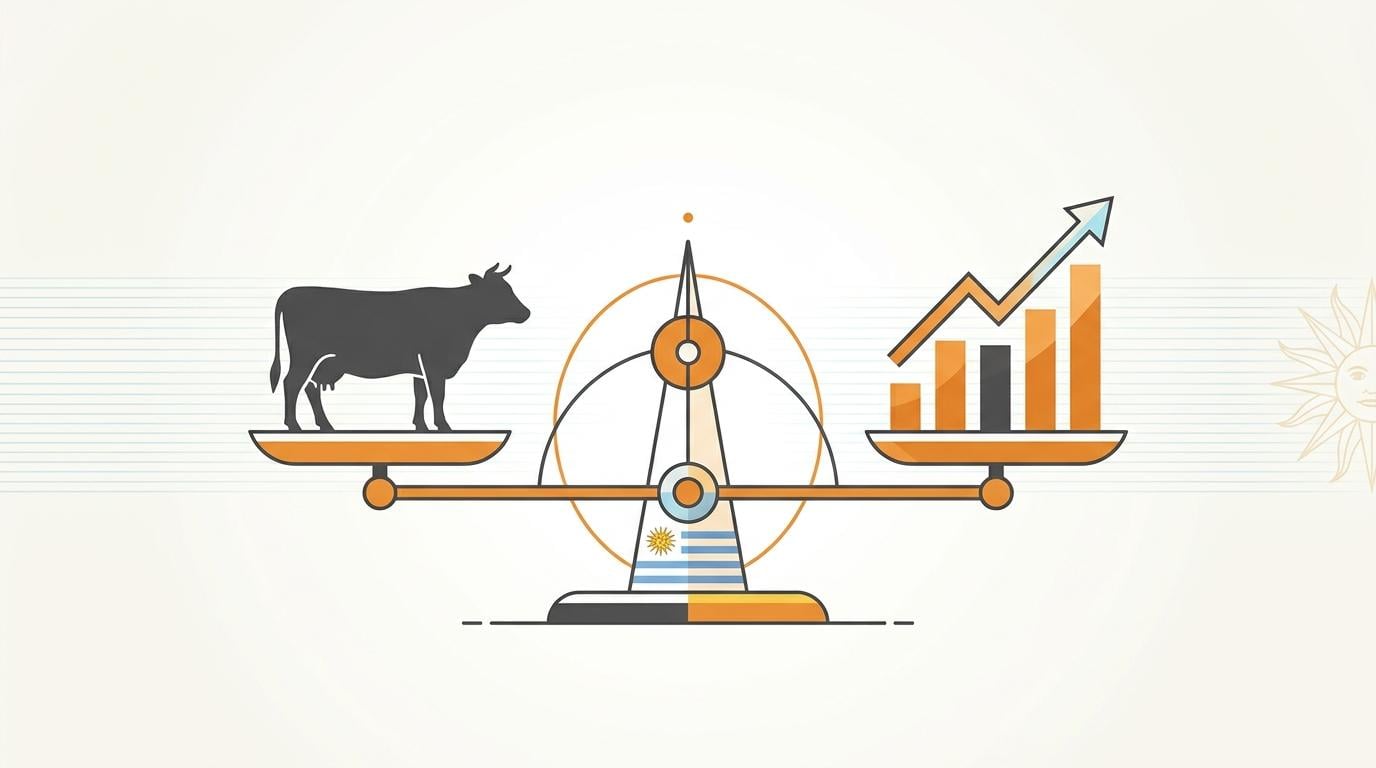
Uruguay’s next sovereign borrowing advantage may depend less on bond auctions than on how efficiently its cattle sector reduces methane. A $350 million World Bank facility now gives Montevideo an interest rate cut of up to 100 basis points if it hits agreed livestock methane intensity targets.
That is not a green bond label. The loan adjusts actual borrowing cost each year based on environmental performance, a first for the World Bank in sovereign lending. The potential saving reaches $12.5 million over the life of the credit, a figure that matters more as fiscal signaling than as balance-sheet relief.
The instrument was shaped jointly by the Ministry of Economy and Finance, the Ministry of Environment and the Ministry of Livestock. Uruguay and the World Bank have spent more than 15 years testing new financing structures. This one moves from disclosure to price.
The commitment dates to 2024, but the World Bank spotlighted the structure in September 2026 as a pioneering model. For an economy that ranks among the world’s top beef exporters, the deal addresses the core tension between agricultural growth and climate commitments.
How the Performance-Linked Contract Works
The mechanism is intentionally direct. As the World Bank details, Uruguay borrows the $350 million, but the interest rate is not fixed in the usual way. A pricing schedule links the annual charge to a specific environmental variable: the methane emitted per unit of livestock production.
If the country cuts that intensity enough, the interest rate falls. The reduction can reach 100 basis points, equivalent to one full percentage point. The maximum saving is capped at the $12.5 million noted above, but the real value is the recurring incentive to keep performance on track.
Three ministries had to align for the design to work. Finance controls the funding strategy. Environment owns the measurement challenge. Livestock carries the operational burden of changing cattle systems. That coordination is the part most investors underprice.
- Trigger: Uruguay must reduce methane emissions intensity in livestock production against agreed targets.
- Reward: The loan’s interest rate falls by up to 100 basis points.
- Frequency: Performance is assessed yearly through the life of the loan, not as a single certification at issuance.
- Ceiling: The maximum interest saving is the $12.5 million already referenced.
The Ministry of Economy and Finance has already signaled that climate adaptation indicators are being integrated into multilateral loan instruments. This performance-linked facility is the clearest example yet of that shift becoming contractual.
Our Read: What This Signals for Sovereign and Property Risk
From our advisory vantage point, the loan matters less as a single liability and more as a signal embedded in Uruguay’s broader debt management. By end-September 2026, central government gross debt stood at 62.5% of GDP and net debt at 58.2%, still below the 65% medium-term anchor.
That debt load has not shrunk in nominal terms. Gross debt rose 2.7 percentage points from end-2025, and net debt rose 2.4 points. But the structure improved. Local-currency debt reached 57.2% of total central government debt, short-term obligations were only 5.5%, and average maturity sat near 11.5 years.
Uruguay’s market access confirms the same story. In July 2026, the sovereign reopened a peso global bond due 2035 at 7.75%, down from 8.0% in the prior issuance. It also reopened a U.S. dollar global bond due 2037 at 5.356% with a spread of 75 basis points over U.S. Treasuries. By October, Uruguay carried the lowest sovereign risk premium in Latin America, around 75 basis points.
Fitch affirmed Uruguay at BBB+ with stable outlook in September 2026. JCR affirmed A- with stable outlook. Those are not upgrades, but they hold the investment-grade platform intact while the Treasury manages projected 2026 financing needs of $6.889 billion.
We read the performance-linked loan as the next layer of that credibility. It does not move a property price on its own. But for an investor deciding whether Uruguay deserves prime-sovereign treatment, a lender willing to price environmental performance into the cost of capital is a meaningful underwriting signal.
It also reinforces a pattern we see in client conversations. Foreign capital increasingly wants both fiscal discipline and proof that institutional quality extends to climate management. Uruguay is packaging both into the same contract.
The Longer Arc for Uruguay’s Investment Case
The takeaway is not that a methane-linked loan will reprice Montevideo apartments overnight. It is that Uruguay keeps widening the gap between its sovereign behavior and the region’s more volatile credits. Institutional investors notice that gap when they allocate across Latin America.
A borrower that can link its interest rate to measurable environmental performance is a borrower with enough confidence in its public institutions to be audited annually. That confidence has already shown up in local-currency debt levels, low short-term refinancing risk and the narrowest sovereign spread in Latin America.
There is one risk on the buying side worth flagging, and it has nothing to do with sovereign debt. Investors entering Uruguay’s real estate market should understand what dual agency means before signing any representation agreement. Dual agency occurs when the same agent acts for both buyer and seller. It creates a structural conflict: the agent’s financial incentive is to keep the sale price high and close quickly, not to negotiate the best possible entry for the investor. In our experience, that can translate into inflated valuations, hidden property liabilities, or a negotiation where the buyer’s interests are never fully represented.
Team Haverkate’s role is to translate signals like this into practical property decisions. A sovereign borrowing instrument may feel distant from a farm purchase in Soriano or an apartment in Montevideo, but the same institutions pricing Uruguay’s environmental performance are also setting the broad risk environment for every asset class. We help international buyers and investors navigate that landscape with local due diligence and a clear-eyed view of where the real risks sit. For clients structuring cross-border entries, we maintain close relationships with vetted local tax and legal specialists.
Frequently Asked Questions
What is Uruguay’s $350 million performance-linked World Bank loan?
It is a $350 million World Bank sovereign lending facility that ties Uruguay’s interest rate to livestock methane intensity targets. If Uruguay reduces methane emissions per unit of livestock production against agreed benchmarks, its interest rate falls by up to 100 basis points, with a maximum saving of $12.5 million over the life of the loan. It is the first World Bank sovereign loan to adjust actual borrowing cost annually based on environmental performance rather than a static green label.
How does a performance-linked loan differ from a green bond?
A green bond typically carries a label and use-of-proceeds commitment but does not change the coupon based on results. Uruguay’s facility reprices the interest rate each year according to a measurable environmental variable: methane emitted per unit of livestock production. The incentive is recurring and contractual, not a one-time certification at issuance.
What methane reduction targets must Uruguay meet to lower its interest rate?
Uruguay must reduce methane emissions intensity in livestock production against agreed annual targets. Performance is assessed yearly through the life of the loan. The reward is an interest rate reduction of up to 100 basis points, capped at $12.5 million in total savings. The specific intensity thresholds are set in the loan’s pricing schedule rather than disclosed as a single headline number.
Why does this loan matter for Uruguay’s sovereign credit profile?
It reinforces Uruguay’s institutional credibility rather than delivering large balance-sheet relief. By end-September 2026, gross central government debt stood at 62.5% of GDP and net debt at 58.2%, below the 65% medium-term anchor. Local-currency debt reached 57.2% of total central government debt, short-term obligations were 5.5%, and average maturity was near 11.5 years. Fitch affirmed BBB+ and JCR affirmed A-, both with stable outlooks. A lender willing to price environmental performance into the cost of capital is a meaningful underwriting signal for investors weighing prime-sovereign treatment.
Which Uruguayan ministries are involved in the methane-linked loan?
Three ministries shaped the instrument: the Ministry of Economy and Finance controls the funding strategy, the Ministry of Environment owns the measurement challenge, and the Ministry of Livestock carries the operational burden of changing cattle systems. That cross-ministry coordination is the part most investors underprice, and it is what makes annual performance assessment credible.
Does Uruguay’s methane-linked loan affect real estate or property risk?
Not directly. It does not reprice Montevideo apartments or farmland on its own. But it strengthens the broad institutional and sovereign risk environment that underpins every asset class. For international buyers, the more immediate property risk is dual agency, where the same agent represents both buyer and seller, creating a structural conflict that can lead to inflated valuations, hidden liabilities, or weak negotiation on the buyer’s behalf.
What is Uruguay’s sovereign risk premium and market access in 2026?
By October 2026, Uruguay carried the lowest sovereign risk premium in Latin America at around 75 basis points. In July 2026, it reopened a peso global bond due 2035 at 7.75%, down from 8.0% previously, and reopened a U.S. dollar global bond due 2037 at 5.356%, a 75 basis point spread over U.S. Treasuries. The Treasury was managing projected 2026 financing needs of $6.889 billion.